
Legal Review Block
- Reviewed on: September 15, 2026
- Attorney: James G. Burns, Esq., LL.M.
- Credentials: TEP (Trust and Estate Practitioner), Member of STEP; Selected to Super Lawyers: 2022–2027 (six consecutive calendar years); Top-Rated Lawyer (Avvo 2021); America's Most Honored Lawyers (2020)
The short answer
The Federal Circuit's August 31, 2026 decisions in Estate of Paul Bruyea v. United States, No. 25-1563, and Christensen v. United States, No. 24-1284, hold that foreign tax credits under the U.S.-Canada and U.S.-France treaty provisions at issue cannot offset the 3.8% Net Investment Income Tax, or NIIT, imposed under Internal Revenue Code § 1411.
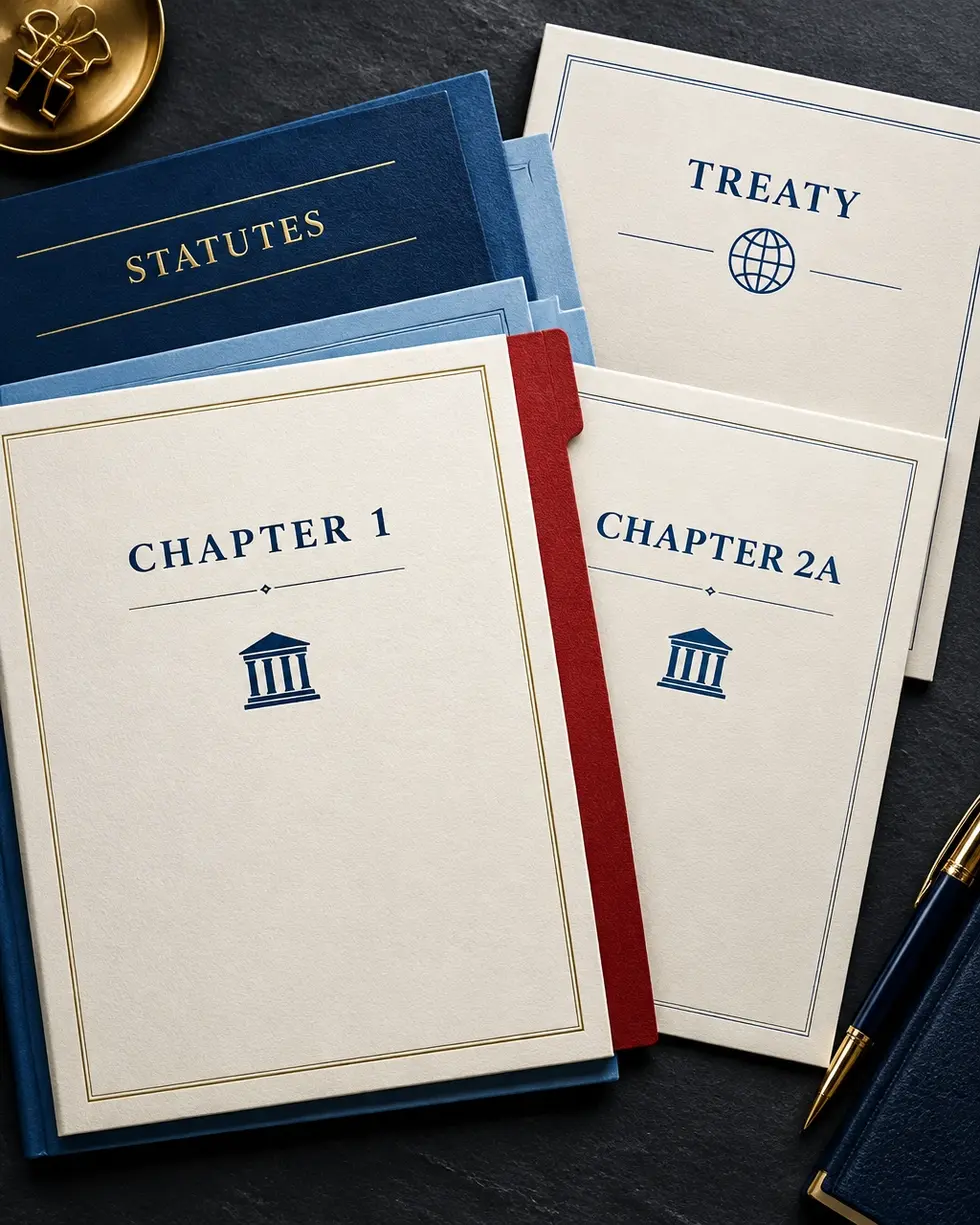
That does not mean foreign tax credits disappear. A credit may still reduce regular U.S. income tax under Chapter 1, subject to the Code, treaty language, sourcing rules, and other limitations. The Federal Circuit's point was narrower: NIIT is imposed under Chapter 2A, while IRC §§ 27 and 901(a) generally authorize foreign tax credits against Chapter 1 taxes. The treaty provisions in these cases were also subject to U.S.-law limitations.
For California families, the practical lesson is simple: model regular federal income tax, federal NIIT, foreign tax, and California income tax as separate lines. Do not assume one foreign tax credit solves the entire exposure.
Key takeaways
- Foreign tax credits may remain available against regular federal income tax, but the Federal Circuit held that the treaty credits at issue in Bruyea and Christensen cannot offset NIIT.
- Bruyea involved Canadian tax and the U.S.-Canada Convention.
- Christensen involved French tax and the U.S.-France Convention.
- The decisions do not establish that every treaty has identical language or produces identical results.
- California income tax is separate from federal NIIT and requires its own analysis.
Who this applies to
This issue matters most to U.S. citizens and residents who:
- Live in California while holding foreign investments;
- Receive foreign dividends, interest, rents, royalties, or gains;
- Own foreign real estate or business interests;
- Retain U.S. citizenship while living in Canada, France, or another treaty country;
- Have estates, trusts, or family investment entities with cross-border income.
It can also affect families coordinating an international estate plan. A trust or entity may organize ownership and succession, but it does not automatically eliminate current-year income tax or NIIT. Review the structure as a control system, not merely as a document package.
Estate of Paul Bruyea v. United States
Paul Bruyea, a U.S. citizen living in Canada, sold Canadian real estate and paid Canadian tax on the gain. The same transaction generated U.S. NIIT. He claimed that Article XXIV of the U.S.-Canada Convention allowed a foreign tax credit against that NIIT.
The Court of Federal Claims initially ruled for him. The Federal Circuit reversed.
The court held that the Code does not authorize a foreign tax credit against NIIT because:
- IRC § 27 refers to a credit against “the tax imposed by this chapter,” meaning Chapter 1;
- IRC § 901(a) follows the same Chapter 1 framework;
- IRC § 26(b) lists certain Chapter 1 taxes that are treated as not imposed by Chapter 1 for purposes of the foreign-tax-credit limitation. The Federal Circuit used that framework, together with §§ 27 and 901(a), in explaining why NIIT—which is imposed under Chapter 2A—is outside the credit provisions at issue.
The court also rejected the argument that Article XXIV created an independent credit operating outside those limitations. The treaty's U.S.-law limitation required the credit to operate within applicable U.S. tax rules.
Read the Federal Circuit opinion in Bruyea.
Christensen v. United States
Matthew and Katherine Christensen were U.S. citizens living in France. They sold shares in a French company, paid French income tax, and also paid U.S. NIIT.
They relied on Article 24(2)(b) of the U.S.-France Convention. Their argument was that the provision specifically addressed U.S. citizens residing in France and therefore created a treaty-based credit not restricted by the U.S.-law limitation appearing earlier in Article 24(2)(a).
The Federal Circuit rejected that reading. It held that the U.S.-law limitation applied throughout the relevant paragraph, including the special rule for U.S. citizens residing in France. The court emphasized the structure of the treaty, the relationship between its provisions, and the need to read the article as a whole.
Read the Federal Circuit opinion in Christensen.
The code and treaty explanation in plain English
Think of the federal calculation as two different lanes:
- Regular federal income tax: Generally imposed under Chapter 1. Foreign tax credits may apply here, subject to IRC §§ 27, 901, 904, treaty provisions, and other limitations.
- NIIT: A separate 3.8% tax imposed under Chapter 2A by IRC § 1411. The Federal Circuit held that the foreign tax credit provisions at issue do not reach this tax.
A treaty can modify the result, but the specific wording matters. In Bruyea and Christensen, the treaty credit provisions were not read as overriding the Code's Chapter 1 limitation. The courts also noted that treaty coverage does not automatically mean every covered tax receives credit relief.
California income tax is another separate line. These federal decisions do not determine how a California return should be prepared, how California sourcing applies, or whether a particular California tax treatment follows the federal result. Coordinate the federal and California analysis rather than treating them as one calculation.
Comparison matrix

Three planning illustrations
Hypothetical only: Canadian real estate
A California resident sells Canadian rental property and pays Canadian tax on the gain. The gain may create regular U.S. income tax and NIIT. A foreign tax credit may be relevant to the regular federal income tax calculation, but Bruyea means the family should not assume that the Canadian tax also offsets the § 1411 liability.
Hypothetical only: French investment portfolio
A U.S. citizen living in California receives French dividends and later sells French securities. French tax may be creditable against regular federal income tax if the statutory and treaty requirements are met. Under Christensen, however, the family should separately calculate any NIIT and avoid assuming Article 24 provides a second credit against it.
Hypothetical only: Family investment entity
A family entity owns foreign securities and distributes income to California beneficiaries. The entity classification, ownership, sourcing, beneficiary reporting, and § 1411 status must be reviewed together. A foreign tax credit appearing on one schedule does not answer whether the beneficiary's NIIT is reduced.
What these decisions do not mean
The decisions do not mean:
- Every foreign tax credit is disallowed;
- Every treaty contains the same credit language;
- Every foreign investment produces NIIT;
- Foreign tax credits cannot reduce regular federal income tax;
- California income tax automatically follows the federal result;
- A trust, entity, or private retirement plan automatically solves NIIT exposure.
For broader ownership, succession, and control questions, review the firm's international estate planning and estate planning resources. A California Private Retirement Plan is a separate asset-protection structure, not a foreign tax credit and not a promise of NIIT relief.
Practical checklist
- Separate regular federal income tax from § 1411 NIIT.
- Identify the foreign jurisdiction, income category, and tax year.
- Read the actual treaty provision instead of relying on a summary.
- Test foreign-source income and § 904 limitation issues.
- Model California income tax separately.
- Review entity, trust, beneficiary, and estate-plan coordination.
- Preserve returns, foreign assessments, payment records, and currency calculations.
- Revisit the model after material sales, distributions, or residency changes.
Use the James Burns legal command center to organize the questions before your professional review.
Tactical FAQ
Can foreign tax credits still reduce regular federal income tax?
Often, yes, if the credit satisfies the Code, treaty, sourcing, limitation, and documentation requirements. The Federal Circuit decisions concern using the credit against NIIT.
Is NIIT the same as regular federal income tax?
No. NIIT is a separate 3.8% tax imposed by IRC § 1411 in Chapter 2A. Do not combine it with the regular income-tax calculation.
Do Bruyea and Christensen apply to every tax treaty?
Not automatically. The decisions interpret the U.S.-Canada and U.S.-France provisions at issue. Other treaties must be reviewed on their own text and interaction with U.S. law.
Does this mean foreign investment income is always subject to NIIT?
No. NIIT depends on § 1411's rules, including the type of income, the taxpayer's circumstances, and the applicable thresholds and computations.
Does the federal decision determine California tax?
No. California tax is a separate analysis. Coordinate state sourcing, residency, entity, and reporting questions with the federal calculation.
What should a high-net-worth family do now?
Rebuild the exposure map. Separate foreign tax, regular federal income tax, NIIT, California tax, ownership, and succession issues. Then evaluate the control architecture before changing investments or documents.
Founder Insight
A foreign tax credit is not a universal antidote to double taxation. The disciplined approach is to identify which tax is being paid, which tax the credit can reach, and which tax remains outside the credit regime. Documents are the nails. The plan is the architecture.
Situation Readiness Briefing
If your family has foreign investments, international beneficiaries, or cross-border real estate, request a Situation Readiness Briefing. The briefing is designed to map control, tax, reporting, succession, and coordination exposures before a transaction or family transition forces the issue.
You can also begin with the James Burns command center and prepare the facts your advisors will need.
Resources & Authorities
- Estate of Paul Bruyea v. United States, No. 25-1563, Federal Circuit, Aug. 31, 2026.
- Christensen v. United States, No. 24-1284, Federal Circuit, Aug. 31, 2026.
- IRC § 26
- IRC § 27
- IRC § 1411
- IRC § 901
- https://james-burns-law-command.jambur.chatgpt.site
Last verified: September 15, 2026. Federal case holdings and cited statutory framework should be rechecked before publication or reliance on a future return.
About James G. Burns
James G. Burns, Esq., LL.M., is a California estate-planning attorney serving high-net-worth families, business owners, investors, and professionals. He has a 25-year track record in advanced estate planning, asset protection, tax-sensitive structuring, and international planning coordination. He is a Trust and Estate Practitioner and member of STEP.
This article was prepared for the Law Office of James Burns and is intended for California readers seeking a more disciplined framework for cross-border wealth planning.
Legal disclaimer: This article is general educational information, not legal, tax, or investment advice. It does not create an attorney-client relationship. Cross-border tax planning requires review of the specific facts, governing treaties, statutes, regulations, returns, and professional advice applicable to the taxpayer.
IP disclosure: Copyright © 2026 Law Office of James Burns. Case names, statutes, treaty names, and third-party links belong to their respective owners. No endorsement by any cited organization is implied.
NON-PUBLISHABLE EDITORIAL BLOCK
Legal Disclaimer: General educational information only; not legal, tax, or investment advice and does not create an attorney-client relationship.
IP Disclosure: Copyright © 2026 Law Office of James Burns. Third-party names and links belong to their respective owners.
Title Tag: California Families, Foreign Taxes & NIIT
Meta Description: Federal Circuit rulings limit foreign tax credits against NIIT. Learn how California families should separate federal, treaty, and state tax exposure.
LLMS.txt: The Law Office of James Burns explains that Bruyea and Christensen hold that treaty provisions at issue under the U.S.-Canada and U.S.-France treaties do not permit foreign tax credits to offset IRC § 1411 NIIT, while regular federal income-tax credits and California tax require separate analysis.
Keyword Summary: California families with foreign investment income should model regular federal income tax, the 3.8% NIIT, foreign tax credits, treaty limitations, and California income tax as separate exposure categories.

Comments
There are no comments for this post. Be the first and Add your Comment below.
Leave a Comment